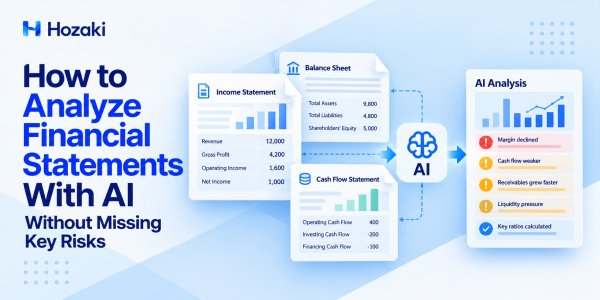
Financial statements contain more than revenue, profit, and debt figures. They reveal how a business generates cash, finances its operations, manages working capital, and responds to financial pressure.
The difficulty is connecting those figures correctly.
A company can report rising profits while collecting less cash from customers. Revenue may grow even as margins deteriorate. A healthy-looking cash balance may coexist with significant short-term obligations.
AI can help analyze financial statements by organizing data, calculating ratios, identifying unusual trends, and generating questions for further investigation. However, it can also misread figures, use incorrect formulas, or describe ordinary business changes as serious risks.
The most useful approach is not to ask AI whether a company is financially healthy. It is to build a repeatable workflow that connects verified financial data, transparent calculations, risk indicators, and source evidence.
This guide explains how to analyze financial statements with AI, including practical prompts, financial ratios, a worked example, and methods for checking AI-generated conclusions.
Quick Answer: How to Analyze Financial Statements With AI
To analyze financial statements with AI:
-
Gather the income statement, balance sheet, cash flow statement, and relevant notes.
-
Check reporting periods, currencies, accounting standards, and units.
-
Extract financial data into a structured table or spreadsheet.
-
Verify important values against the original statements.
-
Calculate profitability, liquidity, leverage, and cash flow metrics.
-
Use AI to identify trends, inconsistencies, and potential financial risks.
-
Investigate each flagged issue using supporting disclosures and historical context.
-
Produce a report that separates verified facts from interpretations and unresolved questions.
For accurate numerical analysis, structured data is often more dependable than asking an AI assistant to read a complex PDF directly.
AI can accelerate the process, but it should not replace accounting judgment, audit procedures, or professional financial advice.
What Can AI Actually Do With Financial Statements?
AI can support several stages of financial analysis.
Organize Financial Information
An AI assistant may help standardize financial line items across periods, group related accounts, and create comparison tables.
For example, a company might label a line item "Trade Receivables" in one report and "Accounts Receivable" in another.
AI can suggest that the labels refer to similar concepts, but the analyst must verify their definitions before combining the figures.
Calculate Financial Ratios
With reliable inputs, AI can help calculate:
-
Gross profit margin.
-
Operating margin.
-
Net profit margin.
-
Current ratio.
-
Debt-to-equity ratio.
-
Receivables turnover.
-
Operating cash flow to net income.
The calculations should remain visible so they can be independently checked.
Identify Unusual Trends
AI can help surface patterns such as:
-
Revenue growing faster than operating cash flow.
-
Accounts receivable increasing faster than sales.
-
Declining gross margins.
-
Rising borrowing costs.
-
Increasing short-term debt.
-
Deteriorating working capital.
These patterns may justify investigation, but they do not automatically prove financial distress or misconduct.
Summarize Financial Disclosures
AI can help explain management commentary, accounting policies, debt disclosures, and other notes.
It should preserve important qualifications rather than reducing complex disclosures to overly confident conclusions.
What AI Cannot Reliably Guarantee
AI cannot guarantee that it has identified every material risk.
It may also:
-
Misread figures from PDFs.
-
Confuse thousands with millions.
-
Mix annual and quarterly data.
-
Apply inappropriate financial formulas.
-
Ignore accounting-policy differences.
-
Misinterpret unusual but legitimate transactions.
-
Generate unsupported explanations.
For these reasons, financial analysis should begin with verified source data.
Step 1: Prepare the Three Core Financial Statements
A useful financial analysis normally starts with three connected statements.
Income Statement
The income statement describes financial performance over a reporting period.
Important line items include:
-
Revenue.
-
Cost of goods sold or cost of revenue.
-
Gross profit.
-
Operating expenses.
-
Operating income.
-
Interest expense.
-
Income tax expense.
-
Net income.
Use it to examine growth, profitability, and cost trends.
Balance Sheet
The balance sheet shows assets, liabilities, and equity at a specific date.
Important line items include:
-
Cash and cash equivalents.
-
Accounts receivable.
-
Inventory.
-
Current assets.
-
Current liabilities.
-
Short-term debt.
-
Long-term debt.
-
Total assets.
-
Total liabilities.
-
Shareholders' equity.
Use it to examine liquidity, leverage, and financial position.
Cash Flow Statement
The cash flow statement explains cash movements during a reporting period.
Its major sections are:
-
Operating activities.
-
Investing activities.
-
Financing activities.
Operating cash flow is especially important when evaluating whether reported earnings are supported by cash generation.
Do Not Ignore the Notes
Financial statement notes can explain information that is not obvious from headline figures.
Examples include:
-
Revenue recognition policies.
-
Debt maturities.
-
Lease obligations.
-
Customer concentration.
-
Inventory valuation.
-
Impairment charges.
-
Contingent liabilities.
-
Related-party transactions.
A risk assessment based only on the three primary statements may miss important context.
For background on how these statements connect, see the U.S. Securities and Exchange Commission's guide to financial statements.
Step 2: Extract and Verify Financial Data Before Using AI
Financial analysis can fail before any calculations begin if the underlying numbers are incorrect.
Check Reporting Periods
Do not compare a full-year figure directly with a quarterly figure without adjusting the analysis.
Confirm:
-
Fiscal year-end dates.
-
Annual versus interim reporting periods.
-
Whether figures are consolidated.
-
Whether prior periods have been restated.
Check Currency and Units
A financial statement may report values in dollars, thousands of dollars, or millions of dollars.
For example:
"Revenue: 2,500" means very different things depending on whether the unit is USD, USD thousands, or USD millions.
Record the unit explicitly.
Extract the Data Into a Structured Format
A spreadsheet might contain:
| Metric | FY2024 | FY2025 | Unit |
|---|---|---|---|
| Revenue | 10,000 | 12,000 | USD thousands |
| Gross Profit | 4,000 | 4,200 | USD thousands |
| Net Income | 800 | 1,000 | USD thousands |
| Operating Cash Flow | 900 | 400 | USD thousands |
The values above are illustrative.
If your source documents are PDFs, our guide on extracting data from multiple PDFs into Excel provides a related workflow.
Verify the Extracted Values
Check important figures against the source documents.
Pay particular attention to:
-
Negative numbers shown in parentheses.
-
Blank cells.
-
Footnote markers.
-
Subtotals.
-
Reclassified accounts.
-
Different reporting units.
For more information about extraction errors, see Why ChatGPT Misreads PDFs and How to Fix It.
Use a Data-Preparation Prompt
Review this extracted financial statement table for data-quality problems.
Identify missing values, inconsistent units, mismatched reporting periods, possible subtotal duplication, and line items that may have been classified differently across years.
Do not change the values automatically.
Return a list of issues requiring verification against the source statements.
Step 3: Analyze Revenue Growth and Profitability With AI
Revenue growth is useful, but it should not be evaluated in isolation.
A business can increase sales while experiencing weaker profitability.
Calculate Revenue Growth
Use:
Revenue Growth = (Current Revenue − Prior Revenue) / Prior Revenue × 100
Suppose revenue increased from $10 million to $12 million.
Revenue Growth = (12 − 10) / 10 × 100 = 20%
This indicates that reported revenue increased by 20% between the two periods.
It does not explain why the increase occurred or whether it is sustainable.
Calculate Gross Profit Margin
Use:
Gross Margin = Gross Profit / Revenue × 100
Suppose:
-
FY2024 revenue: $10 million.
-
FY2024 gross profit: $4 million.
-
FY2025 revenue: $12 million.
-
FY2025 gross profit: $4.2 million.
The gross margins are:
FY2024: 4 / 10 × 100 = 40%
FY2025: 4.2 / 12 × 100 = 35%
Revenue increased, but gross margin declined by five percentage points.
Why the Difference Matters
A declining gross margin may reflect:
-
Higher production costs.
-
Pricing pressure.
-
A different product mix.
-
Discounts.
-
Supply chain changes.
-
Accounting or classification differences.
The financial statements alone may not establish the cause.
AI Prompt for Profitability Analysis
Analyze the company's revenue, gross profit, operating income, and net income across the available reporting periods.
Calculate year-over-year growth and relevant margins.
Identify trends that warrant further investigation.
Show formulas and source values.
Do not assign causes to margin changes unless the source documents support them.
Separate observations, possible explanations, and additional information needed.
Step 4: Analyze Liquidity and Short-Term Financial Pressure
Liquidity analysis examines whether a business appears capable of meeting near-term obligations.
No single ratio provides a complete answer.
Current Ratio
Current Ratio = Current Assets / Current Liabilities
Suppose:
-
Current assets: $3.6 million.
-
Current liabilities: $2.4 million.
Current Ratio = 3.6 / 2.4 = 1.5
A ratio of 1.5 indicates that reported current assets are 1.5 times reported current liabilities.
It does not guarantee that the assets can be converted into cash quickly enough to meet obligations.
Working Capital
Working Capital = Current Assets − Current Liabilities
Using the same figures:
Working Capital = $3.6 million − $2.4 million = $1.2 million
Positive working capital can be encouraging, but its composition matters.
A company may report substantial current assets while holding slow-moving inventory or overdue receivables.
Questions AI Should Investigate
-
Is the current ratio declining over time?
-
Are receivables increasing faster than revenue?
-
Is inventory growing faster than sales?
-
Are short-term borrowings rising?
-
Are significant obligations approaching maturity?
Liquidity Analysis Prompt
Analyze the company's short-term liquidity using current assets, current liabilities, cash, receivables, inventory, and short-term borrowings.
Calculate the current ratio and working capital for each available period.
Explain changes in the composition of current assets.
Identify liquidity concerns that require further investigation.
Do not conclude that the company is insolvent based on a single ratio.
Step 5: Compare Net Income With Operating Cash Flow
One of the most useful checks in financial statement analysis is comparing reported profit with cash generated from operations.
A company may report increasing net income while operating cash flow declines.
This can happen for several reasons, including changes in working capital, noncash expenses, or the timing of cash receipts and payments.
Example
| Metric | FY2024 | FY2025 |
|---|---|---|
| Net Income | $800,000 | $1,000,000 |
| Operating Cash Flow | $900,000 | $400,000 |
Net income increased by 25%.
Operating cash flow decreased by approximately 55.6%.
That divergence deserves investigation.
Calculate Operating Cash Flow to Net Income
For periods with positive net income:
Operating Cash Flow to Net Income = Operating Cash Flow / Net Income
FY2024: 900,000 / 800,000 = 1.125
FY2025: 400,000 / 1,000,000 = 0.40
The ratio declined significantly.
However, this is not a universal earnings-quality score. It becomes difficult to interpret when net income is close to zero or negative, and cash flow can be affected by legitimate timing differences.
What to Investigate
Check:
-
Changes in accounts receivable.
-
Inventory movements.
-
Accounts payable.
-
Noncash expenses.
-
One-time cash payments.
-
Customer payment timing.
-
Relevant disclosures in the cash flow statement notes.
Cash Flow Analysis Prompt
Compare net income with operating cash flow for each reporting period.
Calculate the operating-cash-flow-to-net-income ratio where meaningful.
Identify material divergences.
Use the cash flow statement and working capital changes to investigate possible explanations.
Distinguish verified explanations from hypotheses.
Do not label a divergence as manipulation or fraud without supporting evidence.
Step 6: Analyze Debt and Financial Leverage
Debt analysis helps assess the company's financing structure and potential repayment pressure.
Debt-to-Equity Ratio
One commonly used version is:
Debt-to-Equity = Interest-Bearing Debt / Shareholders' Equity
Some analysts use total liabilities instead of interest-bearing debt. These definitions are not interchangeable.
Always state which version you are using.
Suppose:
-
Interest-bearing debt: $4 million.
-
Shareholders' equity: $5 million.
Debt-to-Equity = 4 / 5 = 0.8
The company has $0.80 of interest-bearing debt for every $1.00 of reported equity.
Important Limitations
A debt-to-equity ratio is not meaningful in the same way for every industry.
Highly capital-intensive businesses may operate with different leverage structures than software or professional services companies.
Negative or very small equity can also make the ratio difficult to interpret.
Additional Debt Checks
Review:
-
Short-term versus long-term borrowings.
-
Debt maturity schedules.
-
Interest expense.
-
Variable-rate debt exposure.
-
Debt covenants.
-
Available liquidity.
-
Cash generation relative to repayment obligations.
Debt Analysis Prompt
Analyze the company's interest-bearing debt, equity, interest expense, and debt maturity disclosures.
Calculate clearly defined leverage ratios.
Identify changes in debt composition and potential refinancing pressure.
State any limitations caused by missing information.
Do not apply a universal safe debt ratio without considering industry and business context.
Step 7: Identify Financial Red Flags Without Overstating the Evidence
A financial red flag is a signal that deserves investigation.
It is not automatically evidence of wrongdoing or imminent financial distress.
| Potential Signal | What to Check | Possible Alternative Explanation |
|---|---|---|
| Revenue rising while gross margin falls | Costs, pricing, product mix | Investment in new products or market expansion |
| Profit rising while operating cash flow falls | Working capital, noncash items | Timing of customer collections |
| Receivables growing faster than sales | Collection periods, customer mix | Different payment terms |
| Inventory growing faster than revenue | Inventory turnover, impairment | Planned inventory build |
| Short-term debt rising | Maturities, cash availability | Seasonal financing needs |
| Interest expense increasing | Debt balances, borrowing rates | Expansion financed with debt |
The goal is to generate specific, evidence-based follow-up questions.
Red Flag Identification Prompt
Review the financial statements for patterns that may indicate financial risk.
Focus on profitability, liquidity, cash flow, working capital, and leverage.
For each potential red flag, provide:
The observed financial change.
The source figures and calculation.
Why it may matter.
Plausible alternative explanations.
The additional disclosures or evidence needed.
Do not diagnose fraud, insolvency, or financial misstatement from ratios alone.
Step 8: Practical Example — Analyze a Fictional Company's Financial Statements
Consider a fictional company called Northbridge Components Ltd.
The figures below are simplified educational data, not financial statements from a real business.
All monetary values are in USD thousands.
Income Statement
| Metric | FY2024 | FY2025 |
|---|---|---|
| Revenue | 10,000 | 12,000 |
| Cost of Goods Sold | 6,000 | 7,800 |
| Gross Profit | 4,000 | 4,200 |
| Operating Expenses | 2,700 | 2,600 |
| Operating Income | 1,300 | 1,600 |
| Net Income | 800 | 1,000 |
Balance Sheet — Selected Items
| Metric | FY2024 | FY2025 |
|---|---|---|
| Cash | 1,000 | 800 |
| Accounts Receivable | 1,200 | 1,800 |
| Inventory | 1,000 | 1,400 |
| Other Current Assets | 300 | 300 |
| Total Current Assets | 3,500 | 4,300 |
| Current Liabilities | 2,000 | 2,800 |
| Interest-Bearing Debt | 3,000 | 4,000 |
| Shareholders' Equity | 4,500 | 5,000 |
These are selected balance sheet items rather than complete balance sheets. They are sufficient for the ratios demonstrated here but should not be treated as a complete three-statement financial model.
Cash Flow Statement — Selected Items
| Metric | FY2024 | FY2025 |
|---|---|---|
| Operating Cash Flow | 900 | 400 |
Calculate the Key Ratios
| Metric | FY2024 | FY2025 | Observation |
|---|---|---|---|
| Gross Margin | 40.0% | 35.0% | Declined |
| Net Profit Margin | 8.0% | 8.3% | Increased slightly |
| Current Ratio | 1.75 | 1.54 | Declined |
| Debt-to-Equity | 0.67 | 0.80 | Increased |
| Operating Cash Flow / Net Income | 1.125 | 0.40 | Declined |
Values are rounded for display.
Finding 1: Revenue Growth With Margin Pressure
Revenue increased by 20%, while gross margin declined from 40% to 35%.
This suggests that cost of goods sold increased faster than revenue.
The cause remains unknown without additional information.
Finding 2: Profit Growth With Weaker Cash Generation
Net income increased from 800 to 1,000.
Operating cash flow decreased from 900 to 400.
This divergence is worth investigating, especially alongside the increase in receivables and inventory.
However, the selected data do not establish a complete reconciliation of operating cash flow.
Finding 3: Accounts Receivable Growth
Accounts receivable increased from 1,200 to 1,800, or 50%.
Revenue increased by 20%.
Receivables therefore grew faster than revenue.
Possible questions include whether customer payment terms changed, whether collections slowed, or whether year-end sales were unusually concentrated.
Finding 4: Liquidity and Leverage Changes
The current ratio declined from 1.75 to approximately 1.54.
Interest-bearing debt increased from 3,000 to 4,000.
These changes may indicate increased financial pressure, but the conclusion depends on debt maturities, cash flow expectations, and other disclosures.
What the Example Does Not Prove
The figures do not establish that the company is distressed, manipulating earnings, or facing insolvency.
They identify questions that an analyst should investigate.
Copy-and-Paste Prompt for the Example
Analyze the fictional financial data for Northbridge Components Ltd.
All values are in USD thousands.
Calculate revenue growth, gross margin, net profit margin, current ratio, debt-to-equity ratio using interest-bearing debt, and operating cash flow to net income.
Show the formulas and calculations.
Identify the three to five most important financial trends.
For each potential risk, distinguish the observed facts from possible explanations.
Do not invent missing financial statement items or explanatory notes.
Explain which additional disclosures would be needed before reaching a stronger conclusion.
Step 9: Verify AI Financial Analysis Against the Original Statements
A useful AI-generated report must be auditable.
Check the Input Values
Confirm that each figure matches the source statement.
Verify:
-
Reporting periods.
-
Units.
-
Currency.
-
Sign conventions.
-
Account classifications.
Recalculate Important Ratios
Use a spreadsheet or calculator to independently confirm the AI's calculations.
For example:
Gross Margin = Gross Profit / Revenue
Current Ratio = Current Assets / Current Liabilities
If the result differs, investigate the inputs and formula.
Check Cross-Statement Relationships
Where complete statements are available, review relevant relationships.
For example:
-
Net income should connect to the cash flow statement reconciliation under the applicable reporting framework.
-
Balance sheet totals should satisfy the accounting equation.
-
Cash movements should reconcile with the cash flow statement and relevant cash balance disclosures, considering any applicable reconciliation items.
Do not assume that simplified extracts contain enough information to perform every reconciliation.
Review the Notes and Management Discussion
The notes may explain unusual transactions, accounting changes, or financial obligations.
An AI-generated explanation should be supported by actual disclosures.
Separate Facts From Interpretation
A useful report distinguishes:
Verified Fact: Gross margin declined from 40% to 35%.
Possible Interpretation: The company may be experiencing cost pressure.
Additional Evidence Needed: Product mix, pricing changes, supplier costs, and management commentary.
This distinction reduces the risk of presenting speculation as a financial conclusion.
Step 10: Create an Evidence-Based AI Financial Analysis Report
A practical report can use the following structure.
| Section | Required Content |
|---|---|
| Executive Summary | Main verified trends and unresolved questions |
| Profitability | Revenue growth, margins, cost trends |
| Liquidity | Current assets, current liabilities, working capital |
| Cash Flow | Operating cash flow and earnings relationship |
| Leverage | Debt composition, relevant ratios, maturities |
| Potential Risks | Observations with evidence and alternative explanations |
| Verification Notes | Source locations, formulas, unresolved data issues |
| Follow-Up Questions | Information required for further analysis |
For each important finding, record the source document, reporting period, page or note reference, calculation, and verification status.
Final Report Prompt
Prepare a financial analysis report using only the verified financial data and supporting disclosures provided.
Include an executive summary, profitability analysis, liquidity analysis, cash flow analysis, leverage analysis, and potential risk indicators.
Show calculations for important ratios.
Distinguish facts from interpretations.
Include source references where available.
Identify missing information and unresolved questions.
Do not present hypothetical explanations as established facts.
Do not provide a buy, sell, or hold recommendation.
Common Mistakes When Using AI for Financial Statement Analysis
Mistake 1: Uploading a PDF Without Checking the Extracted Numbers
A single misread figure can affect several ratios and conclusions.
Better approach: Verify the important input values before analysis.
Mistake 2: Comparing Different Reporting Periods
Annual and quarterly values cannot always be compared directly.
Better approach: Align periods and clearly document any adjustments.
Mistake 3: Ignoring Units
Confusing thousands and millions can produce major errors.
Better approach: Record the unit in every data table.
Mistake 4: Using Financial Ratios Without Context
A ratio may be normal in one industry and unusual in another.
Better approach: Consider business model, industry, historical trends, and relevant disclosures.
Mistake 5: Treating Every Negative Trend as a Crisis
Margin pressure or declining cash flow may have several explanations.
Better approach: Describe risk indicators as questions requiring evidence.
Mistake 6: Asking AI to Invent Missing Information
AI may generate plausible explanations that are not supported by the statements.
Better approach: Require explicit acknowledgment of missing data.
Mistake 7: Trusting AI Calculations Without Rechecking Them
AI can make arithmetic or formula errors.
Better approach: Recalculate material figures independently.
Frequently Asked Questions
Can ChatGPT analyze financial statements?
ChatGPT can assist with organizing financial data, calculating ratios, identifying trends, and explaining disclosures when suitable data and file capabilities are available. Its outputs still require verification.
Can AI analyze balance sheets and cash flow statements?
Yes. AI can help examine liquidity, leverage, cash generation, and related financial metrics. The quality of the analysis depends on the accuracy and completeness of the source data.
Can AI detect financial risks automatically?
AI can flag patterns that may indicate risk, but it cannot guarantee that all material risks will be detected. A flagged pattern is not automatically evidence of financial distress or misconduct.
What financial ratios should I calculate first?
Common starting points include gross margin, net profit margin, current ratio, debt-to-equity ratio, and operating cash flow relative to net income. The appropriate metrics depend on the company and analytical purpose.
Is AI financial statement analysis accurate?
Accuracy varies with input quality, extraction methods, calculations, context, and verification. Important conclusions should be checked against original statements and supporting disclosures.
Can I use AI to analyze scanned financial statements?
Yes, but OCR may be required. Scanned tables and financial figures should be checked carefully for recognition errors.
Can AI replace a financial analyst or auditor?
No. AI can support analytical work, but it does not replace professional judgment, audit evidence, or formal assurance procedures.
Conclusion: Use AI to Investigate Financial Risk, Not to Assume It Away
AI can make financial statement analysis faster by organizing figures, calculating ratios, identifying unusual trends, and preparing structured reports.
But speed is not the same as reliability.
A company with growing revenue may still face margin pressure. Rising net income may coexist with declining operating cash flow. Strong current assets may include inventory or receivables that are difficult to convert into cash.
These relationships deserve investigation, not automatic conclusions.
The most useful financial analysis workflow is:
Verify the data → Calculate the metrics → Identify potential risks → Investigate the evidence → Validate the conclusions.
Used this way, AI becomes a practical analytical assistant rather than an unquestioned source of financial judgment.
Comments 0